Financial pressure is a reality for many Australians right now.
Higher household costs, interest rates and other financial pressures can put significant strain on individuals and families. Of course, financial pressure does not mean someone will commit fraud. Most people experiencing financial difficulty will never do anything dishonest.
But from a fraud risk perspective, pressure matters.
One useful way of understanding occupational fraud is the fraud diamond. It extends the traditional fraud triangle by considering four factors that may come together when fraud occurs:
Pressure. Opportunity. Rationalisation. Capability.
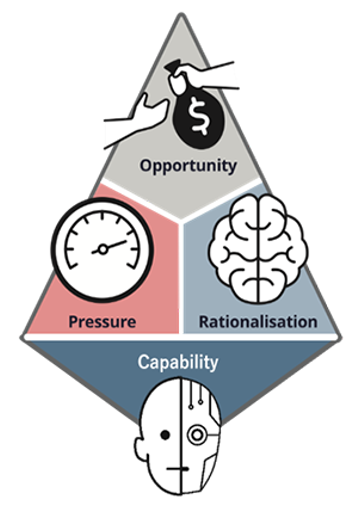
Source: www.counterfraud.gov.au
Financial difficulty can create pressure.
Weak financial controls can create opportunity.
A person may rationalise their actions: I’ll pay it back. They owe me. It’s only temporary. No one will notice.
And then there is capability. Does the person have the access, authority, knowledge and ability to commit the fraud and potentially conceal it?
For businesses and their advisors, this is important.
The question isn’t just “Who in our business might be under financial pressure?”
But instead, the question morphs into
Where could financial pressure combine with access, opportunity and weak controls to create a fraud risk?
And that is something every business can review now, and proactively do something about.
What should business owners be watching?
Fraud rarely announces itself with one obviously fraudulent transaction.
More often, it is a series of small warning signs. Individually, they may have perfectly reasonable explanations. Together, they may tell a different story.
Here are some of the red flags I would be watching.
1. One person has too much control
Consider who can:
- create new suppliers
- change supplier bank details
- approve invoices
- process payments
- change payroll details
- issue refunds or credits
- make journal entries
- perform bank reconciliations.
If several of those functions sit with the same person, you potentially have both opportunity and capability.
This is particularly common in smaller businesses, where segregation of duties can be difficult.
The answer doesn’t have to be complicated. Independent approval of new suppliers and bank detail changes, dual authorisation for payments and regular review of bank reconciliations can significantly reduce the opportunity for fraud.
2. Changes in someone’s personal circumstances
Financial difficulties, significant debts, gambling problems, unexpected expenses or other changes in personal circumstances may sometimes indicate increased financial pressure.
But this needs to be treated carefully.
Personal financial difficulty is not evidence of fraud.
It becomes more relevant from a fraud-risk perspective when pressure exists alongside other warning signs, particularly unusual transactions, behavioural changes, access to money or weaknesses in financial controls.
The focus should remain on the business’s controls and the financial evidence.
3. Someone won’t let go of a process
A person who rarely takes leave, resists having somebody else perform their duties, becomes unusually protective of particular records or insists on maintaining sole control of a financial process may warrant closer attention.
Again, there may be an entirely innocent explanation.
But consider the fraud diamond. If a fraud requires ongoing manipulation of records or explanations to conceal it, the person responsible may need to remain closely involved in that process.
That is where capability becomes particularly relevant.
4. Transactions that don’t quite make sense
Pay attention to:
- duplicate payments
- unusually round-dollar payments
- new suppliers with little supporting information
- unexplained changes to supplier bank accounts
- payments repeatedly just below approval limits
- unusual refunds, credits or write-offs
- unexplained changes to employee bank details
- payments at unusual times
- multiple suppliers being paid into the same bank account
- frequent manual journals or adjustments
- missing or inconsistent supporting documents.
None of these proves fraud.
But if something doesn’t make commercial sense, ask the question.
Sometimes fraud is discovered because someone finally asks “Why are we paying this?”
5. Controls that exist on paper but not in practice
Having a fraud control is not the same as actually operating it.
Approval processes gradually become a rubber stamp. Passwords are shared. Supplier bank details aren’t independently verified. Bank reconciliations are prepared and reviewed by the same person. Payment batches are approved without anyone checking the underlying invoices.
These shortcuts can become normal over time.
They can also create opportunity.
A useful stress test for business owners is to ask when was the last time we checked that those controls are actually being followed?
What should you do if you find something?
If something doesn’t look right, the instinct may be to confront the person involved and ask for an explanation.
Pause before you do.
If fraud has occurred, an early confrontation can make an investigation more difficult. Documents can disappear, electronic records can be altered and funds can be moved.
Instead, take a measured approach.
Preserve the evidence
Secure relevant accounting records, emails, bank statements, invoices, payment records and other electronic information.
Where possible, preserve the original records rather than simply printing or exporting selected documents.
Protect the business from further loss
Consider whether banking authorities, payment limits or access to financial systems need to be changed.
This needs to be handled carefully. The priority is to reduce the possibility of further loss without inadvertently compromising evidence.
Don’t jump to conclusions
A suspicious transaction isn’t necessarily a fraudulent transaction.
The first objective should be to establish the facts: what happened, who had access, where the money went and whether the business has suffered a loss.
A proper investigation should test the evidence rather than start with a conclusion.
Speak with your insurance broker early
If you hold crime, fidelity or another potentially responsive insurance policy, speak with your insurance broker as early as possible.
There may be notification requirements under the policy and the insurer may have requirements around the investigation, preservation of evidence or costs incurred.
This is particularly important before launching a substantial investigation or incurring significant professional fees.
If forensic accounting assistance is required, your insurance broker can call us.
We can work with the broker, insured and insurer to understand what has happened, preserve and analyse the financial evidence, trace transactions, quantify the loss and assist with documenting the insurance claim.
You don’t need to have all the answers
One of the most important things for business owners to understand is that you don’t need to prove fraud before raising a concern.
Often, it starts with something much simpler: a feeling or knowing that something doesn’t add up.
Getting advice early can help preserve evidence, prevent further loss and give the business a clearer understanding of what has happened.
Financial pressure alone does not cause fraud. But when pressure combines with opportunity, rationalisation and capability, the risk changes.
For Australian businesses, the practical response isn’t to become suspicious of employees who may be experiencing financial difficulty. It is to make sure your controls are working, pay attention when something doesn’t look right and know what to do if you find it.
And if you do find something, preserve the evidence and speak with your insurance broker. If specialist forensic assistance is needed, they can call us.